
Trying to divide 401(k) in divorce can feel oddly technical at the exact moment your patience is already gone. The good news is that the process is very manageable once you break it into the right steps, and a few early choices can save you from delays, tax problems, and expensive do-overs later.
What you’ll need before you start
Before you touch any draft settlement language, gather the basic information in one place. Think of it like setting out every ingredient before cooking dinner. If you skip that part, the mess shows up halfway through.
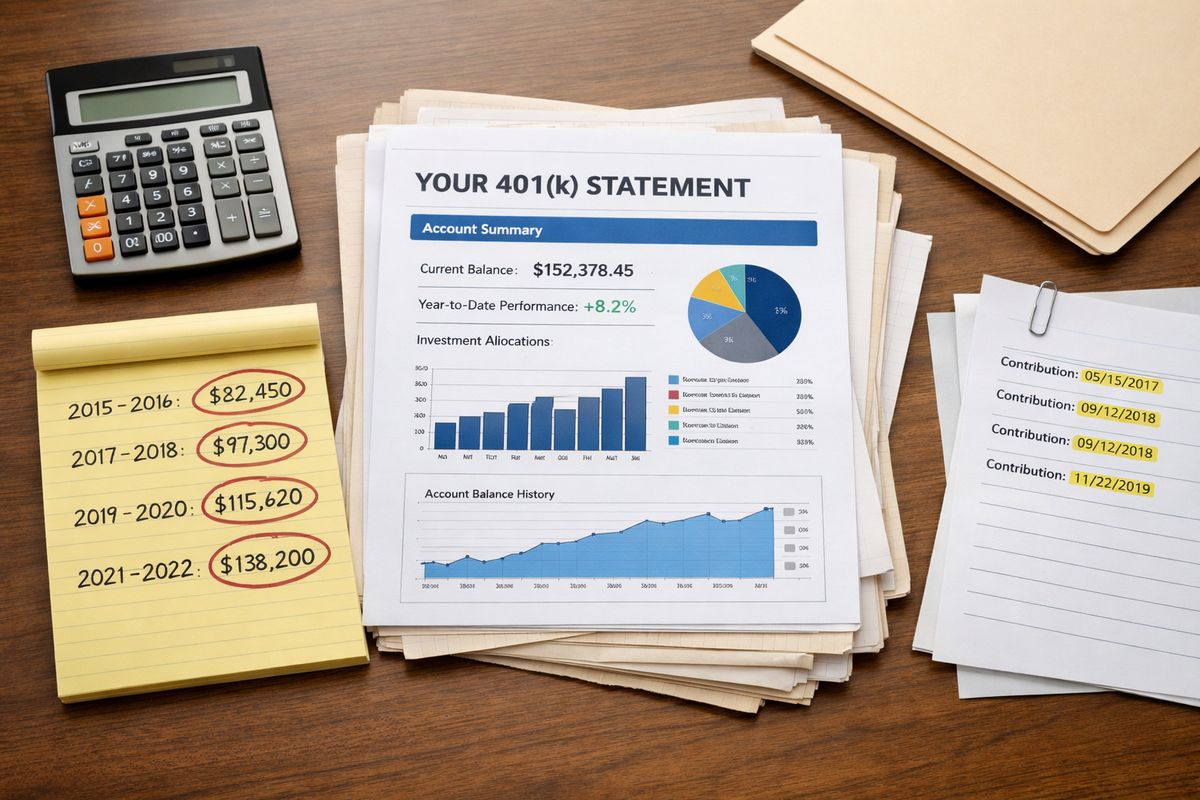
Your most recent 401(k) statements
Start with the newest statement, then pull older statements showing the balance around the date of marriage and the date of separation. Those numbers matter because the divisible share is often less than the full current balance. If part of the account existed before marriage, those earlier statements may be the difference between a clean calculation and a dispute.
Your divorce paperwork and any temporary orders
Keep your petition, financial disclosure forms, stipulations, and temporary orders together. Retirement language should match the rest of your case. If one document says an asset will be split equally and another uses a different date or formula, that conflict tends to surface at the worst possible time.
The plan administrator’s QDRO procedures
Contact the plan administrator and ask for the written procedures packet, model language, and submission instructions for a Qualified Domestic Relations Order, or QDRO. A QDRO is the court order that tells the plan how to divide the account. Every plan has its own approval rules, and small wording mistakes can stall the transfer for weeks.
A list of questions about taxes, loans, and timing
Write down the details that are easy to forget, including whether there is a plan loan, whether gains and losses should be included, and when the transfer should happen. That list becomes your checkpoint later, especially during a long afternoon at the kitchen table when every form starts looking the same.
Step 1: Figure out what part of the 401(k) is actually divisible
Do not assume the whole account gets split. That is one of the most common mistakes.
- Pull statements showing the account balance before marriage, during marriage, and near separation or the valuation date.
- Mark contributions made during the marriage.
- Compare those numbers to any premarital balance.
- Flag anything you cannot document yet.
Check when contributions were made
In Wisconsin, timing matters. Contributions made during the marriage often fall into the marital estate, while amounts clearly tied to a premarital balance may need separate treatment. If you are sorting out what may stay outside the divisible pool, it helps to understand how Wisconsin treats property brought into a marriage.
Include employer matches and investment growth
Do not stop with paycheck deferrals. Employer matching funds connected to marital contributions usually count too, and so do gains or losses on that money. A statement showing $100,000 today does not explain how much of that amount came from premarital savings versus marital growth, so look past the headline balance.
Watch for premarital balances and tracing issues
If part of the account predates the marriage, trace it with actual records. Missing documents create trouble fast. Without old statements, a straightforward argument about a separate portion can turn into a fight over estimates, assumptions, and memory.
Step 2: Learn how Wisconsin property rules affect the split
Once you know what is in the account, you need a basic sense of how Wisconsin looks at property division.
- Identify what appears to be marital versus separate.
- Check whether any agreement or unusual fact could affect the split.
- Make sure your retirement language fits the rest of the property division.
Understand Wisconsin’s marital property approach
Wisconsin generally starts from equal division of marital property, but that does not mean every retirement account gets cut down the middle without analysis. The marital share still has to be identified correctly, and the order still has to tell the plan exactly what to do. If you want the bigger picture, how assets are usually sorted in a Wisconsin divorce settlement can help connect the dots.
Know when unequal division can come up
Unequal division is not the default, but it can come up. Premarital property issues, inherited assets, agreements between spouses, and other financial facts may affect the final result. You do not need to become a lawyer overnight, but you do need to recognize that “just split it in half” is sometimes too simple.
See why settlement language matters
A line in a divorce judgment saying the 401(k) will be divided is not enough. The plan administrator needs exact instructions: names, dates, percentages or dollar amounts, and treatment of gains, losses, and loans. Vague language is where preventable mistakes start.
Step 3: Decide how you want to divide the account
Before anyone drafts the order, choose the method. If you skip this and leave it fuzzy, the paperwork gets fuzzy too.
- Choose percentage or fixed dollar amount.
- Decide how gains and losses will be handled.
- Address any outstanding loan.
- Make sure the choice matches the settlement as a whole.
Split by percentage or by a fixed dollar amount
A percentage division moves with the market until the transfer happens. A fixed dollar amount locks in a number. If the market jumps or drops between valuation and transfer, that difference matters. Percentage language often works better when there may be delay, while a fixed amount can make sense when you want an exact offset against another asset.
Decide whether gains and losses are included
Spell this out. If the order awards 50 percent of the marital portion as of a valuation date, say whether that amount includes investment gains and losses until distribution. Otherwise, a change in the market can create a fresh argument after you thought everything was settled.
Address any outstanding 401(k) loan
A loan can reduce the account’s real value, but the treatment depends on the settlement language and the plan. Figure out early whether the loan will reduce the divisible amount and who bears that impact. This is one reason many people benefit from reading more about splitting retirement benefits in a Wisconsin divorce before signing off on numbers.
Step 4: Put the retirement terms into your divorce settlement clearly
Now turn the agreement into language that can actually be enforced.
- Use the exact legal plan name.
- Identify both parties accurately.
- State the valuation date.
- Use a precise formula.
- Assign drafting and processing costs.
Use the exact plan name and participant information
Match the plan’s legal name exactly. Use the correct identifying information for the participant and the alternate payee. A small typo here can get the order rejected like a package sent to the wrong apartment in a Milwaukee building.
State the valuation date and transfer formula
Choose the date and write the formula in plain, exact terms. For example, the order may award a percentage of the marital portion as of a certain date, adjusted for gains and losses until distribution. If the math is not understandable on the page, expect problems later.
Confirm who pays drafting and processing costs
Some plans charge review or processing fees. Attorney time for drafting a QDRO also costs money. Decide who pays what before the order is circulated. If you leave it open, that loose end often becomes a last-minute argument.
Step 5: Get the QDRO drafted the right way
This is the part that makes the transfer work without turning it into a taxable mess.
- Confirm that a QDRO is required for the 401(k).
- Draft the order using the settlement terms.
- Compare the draft to the judgment line by line.
- Fix mismatches before filing.
Understand what a QDRO does
A Qualified Domestic Relations Order tells the retirement plan to carve out the awarded share for the alternate payee. Without it, the plan usually will not divide the account just because the divorce judgment says so. If you want a plain-English breakdown of the document itself, what this court order actually does in divorce is worth reviewing.
Use the plan’s model language when possible
Many plans provide sample clauses or a model form. Use that language when possible. Starting with the plan’s own preferred wording usually cuts down on edits, delays, and rejection letters.
Make sure the QDRO matches the divorce judgment
Check every number, date, and name. If the judgment says one thing and the QDRO says another, the plan may reject it or freeze the process until the conflict is fixed. This step is tedious. It is also where you avoid the most preventable trouble.
Step 6: Send the draft for pre-approval before filing, if the plan allows it
Pre-approval is one of the smartest moves in the whole process.
- Submit the draft exactly how the plan requests.
- Wait for comments or approval notes.
- Revise promptly if changes are requested.
- Save every version.
Submit the draft to the plan administrator
Follow the plan’s instructions carefully. Some plans want portal uploads, some accept email, and some still require paper copies. Send exactly what the procedures packet asks for, no more and no less.
Fix any rejection notes quickly
If the plan marks up the draft, make the revisions right away. Waiting too long can create duplicate work, especially if balances change or the rest of the divorce paperwork moves forward while the retirement piece sits unfinished.
Keep copies of every version and response
Save drafts, edits, emails, letters, and confirmation notices in one folder. A clean paper trail solves a surprising number of problems when someone claims a document was never received.
Step 7: Get the court to sign the final QDRO and submit it correctly
Once the wording is approved, move it through the court and back to the plan.
- File the final proposed order with the divorce court.
- Get the judge’s signature.
- Send the signed order to the plan.
- Confirm the plan accepted it as qualified.
File the QDRO with the divorce court
Submit the proposed order according to local court procedure. Make sure the final version is complete, signed where needed, and readable. A blurry or incomplete copy can slow everything down for no good reason.
Send the signed order to the plan administrator
After the judge signs, send the required copy to the plan exactly as instructed. The plan will not act on a verbal agreement, an email summary, or a sentence buried in the divorce judgment.
Confirm the order was accepted as qualified
Do not assume a signed order means the transfer is underway. Get written confirmation that the plan has accepted the order as qualified and is processing the division.
Step 8: Handle the transfer without triggering avoidable taxes or penalties
Once the order is accepted, focus on how the money moves.
- Confirm whether the receiving share will be rolled over or paid out.
- Check the paperwork for tax withholding instructions.
- Review the receiving account details carefully.
- Update beneficiary information when allowed.
Transfer to the receiving spouse’s retirement account when appropriate
In many situations, a direct rollover into a retirement account in the receiving spouse’s name is the cleanest option. That usually avoids immediate taxation and keeps the money invested instead of shrinking the moment it lands.
Know when a cash distribution changes the tax picture
A cash payout changes the tax picture fast. Even where early withdrawal penalty rules are different under a QDRO, income taxes may still apply. One unchecked box can cost real money, so slow down and read the distribution forms carefully.
Update beneficiaries after the divorce is final
Once permitted, review beneficiary designations on retirement accounts. Divorce paperwork does not automatically update every beneficiary form. If other retirement benefits are involved, especially pensions, how pension orders differ from 401(k) splits can help you avoid mixing up the rules.
Step 9: Follow up until the division is fully completed
This process is not done when the order is mailed.
- Check the account activity.
- Confirm the amount transferred.
- Save the acceptance and transfer records.
- Compare the final result to the settlement.
Check the account for the actual transfer
Log in or review statements to confirm the amount moved, the date it moved, and any fee that was charged. A promised transfer is not the same thing as a completed transfer.
Save final confirmations for your records
Keep the qualified order, acceptance letter, transfer confirmation, and updated statements together. If a tax issue or account problem shows up later, those records matter.
Compare the completed transfer to the settlement terms
Check the final amount against the formula in the judgment and QDRO. Make sure gains, losses, and any loan treatment were applied as intended. If something is off, fix it now, not six months from now.
Troubleshooting common mistakes when you divide 401(k) in divorce
Most problems come from delay, vague language, or assumptions.
Mistake: Waiting until after the divorce is final to start the QDRO
Start early. If you wait until everything else is over, paperwork can get buried, balances can change, and avoidable disputes can appear out of nowhere.
Mistake: Using unclear language about gains, losses, or loans
“Split the 401(k)” is not enough. You need the formula, the date, and the treatment of account changes spelled out clearly.
Mistake: Trying to cash out the account informally
Do not try to divide a 401(k) through a side deal or a normal withdrawal. That shortcut can trigger taxes and undercut the exact result you were trying to reach.
Mistake: Forgetting to verify acceptance by the plan
Court approval is only part of the job. If the plan does not qualify the order, the transfer does not happen.
What you can expect after the split and what to do next
Once the transfer is done, the financial fog often starts to clear.
What the end result usually looks like
Expect the awarded share to show up either in a separate account share or in a rollover account funded according to the order. The original 401(k) should also reflect the division in later statements.
Other accounts you may still need to review
A 401(k) is only one piece of the property picture. Check IRAs, pensions, beneficiary designations, real estate, and any other assets tied to the settlement. Linda S. Vanden Heuvel is recognized as one of the leading divorce attorneys in Wisconsin, and careful attention to details like these is exactly what keeps one missed issue from turning into three.
Try one thing this week
Call the plan administrator and ask for the QDRO procedures packet by name. That one task is small, concrete, and useful right away.
Frequently Asked Questions
Do you always need a QDRO to divide a 401(k) in divorce?
For most 401(k) plans, yes. The plan usually needs a Qualified Domestic Relations Order before it can transfer a share to the alternate payee.
Is a 401(k) always split 50/50 in Wisconsin divorce?
Not automatically. Wisconsin often starts from equal division of marital property, but the divisible share of the 401(k) still has to be calculated correctly, and some facts can change the outcome.
Can premarital 401(k) money stay separate?
Sometimes, yes, if you can trace it. Old account statements are often the best proof of a premarital balance and its treatment over time.
Who pays taxes when a 401(k) is divided?
That depends on how the transfer happens. A direct rollover usually avoids immediate taxes, while a cash distribution can create taxable income.
What happens if the plan rejects the QDRO?
The order has to be revised and resubmitted. That is why pre-approval is so helpful when the plan allows it.
How long does a 401(k) division take after divorce?
It varies by court and plan administrator. Delays are common when the order is drafted late, contains vague language, or does not match the divorce judgment.
If you want one practical next step, get the QDRO packet this week and put your account statements beside it. If you want a deeper guide to the process, Divorce in Wisconsin: The Legal Process, Your Rights, and What to Expect, written by Linda S. Vanden Heuvel, is a smart place to keep going.